
Loans Longer Than Presidential Terms
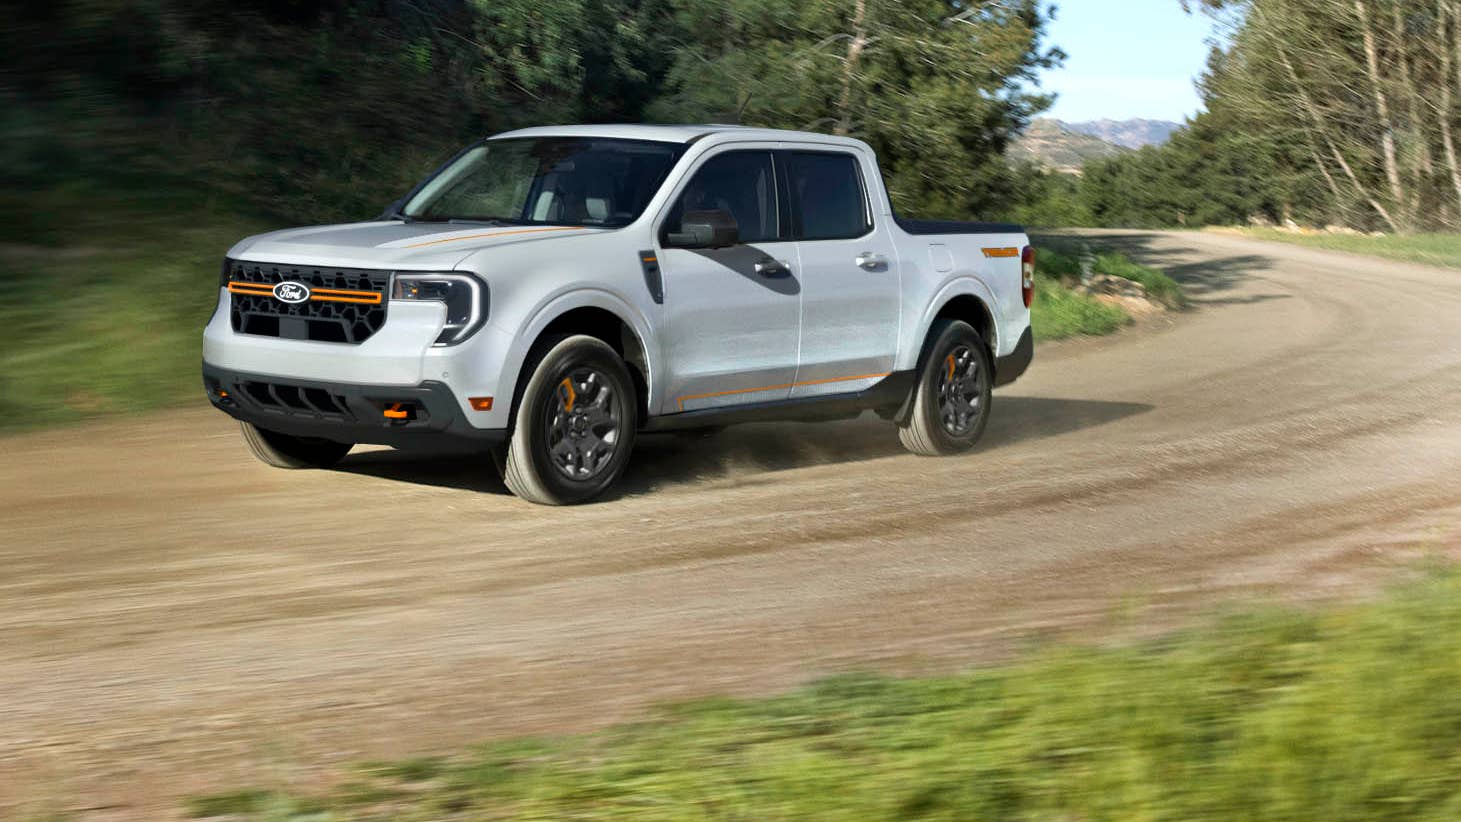
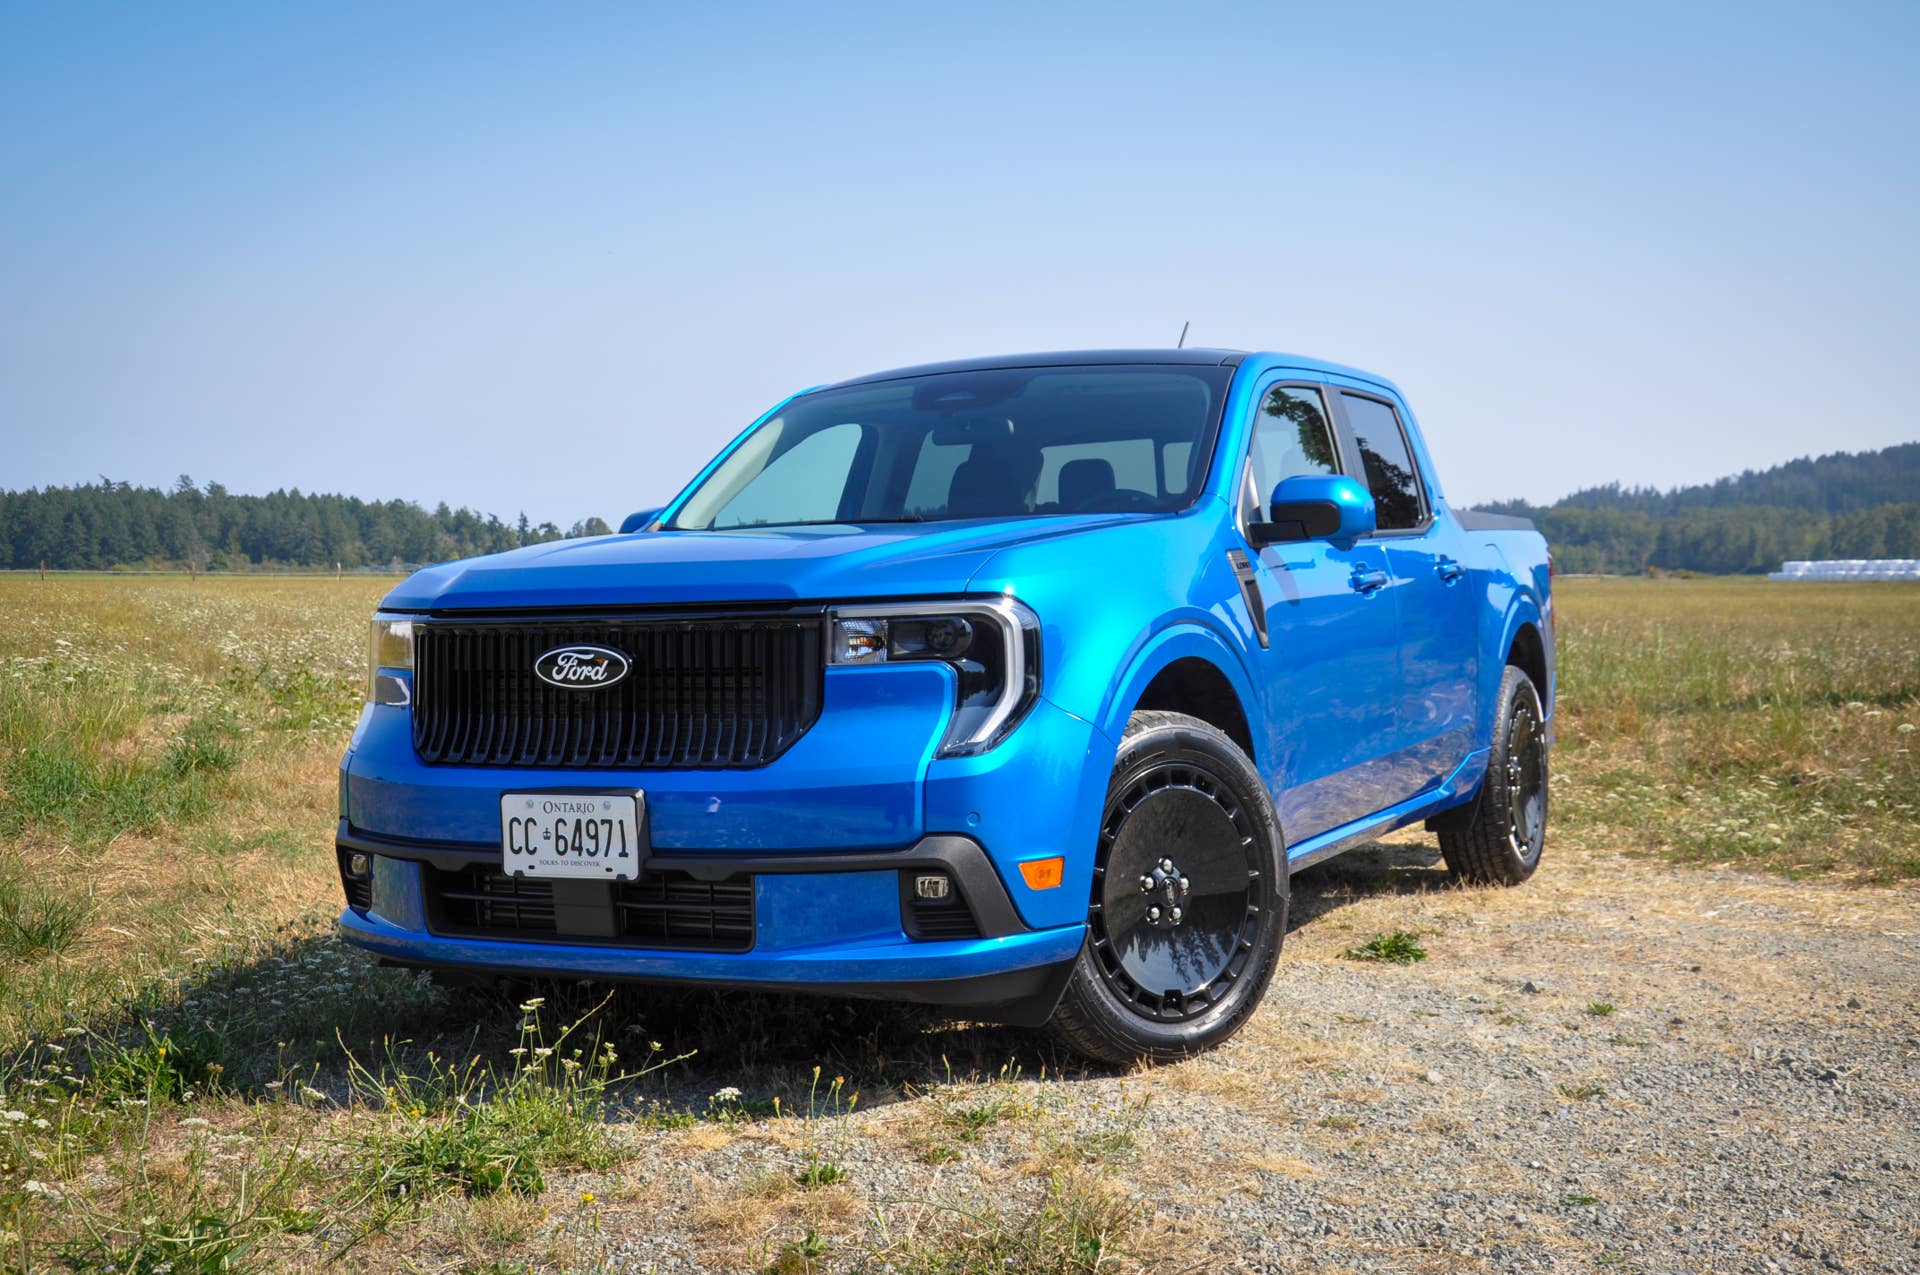
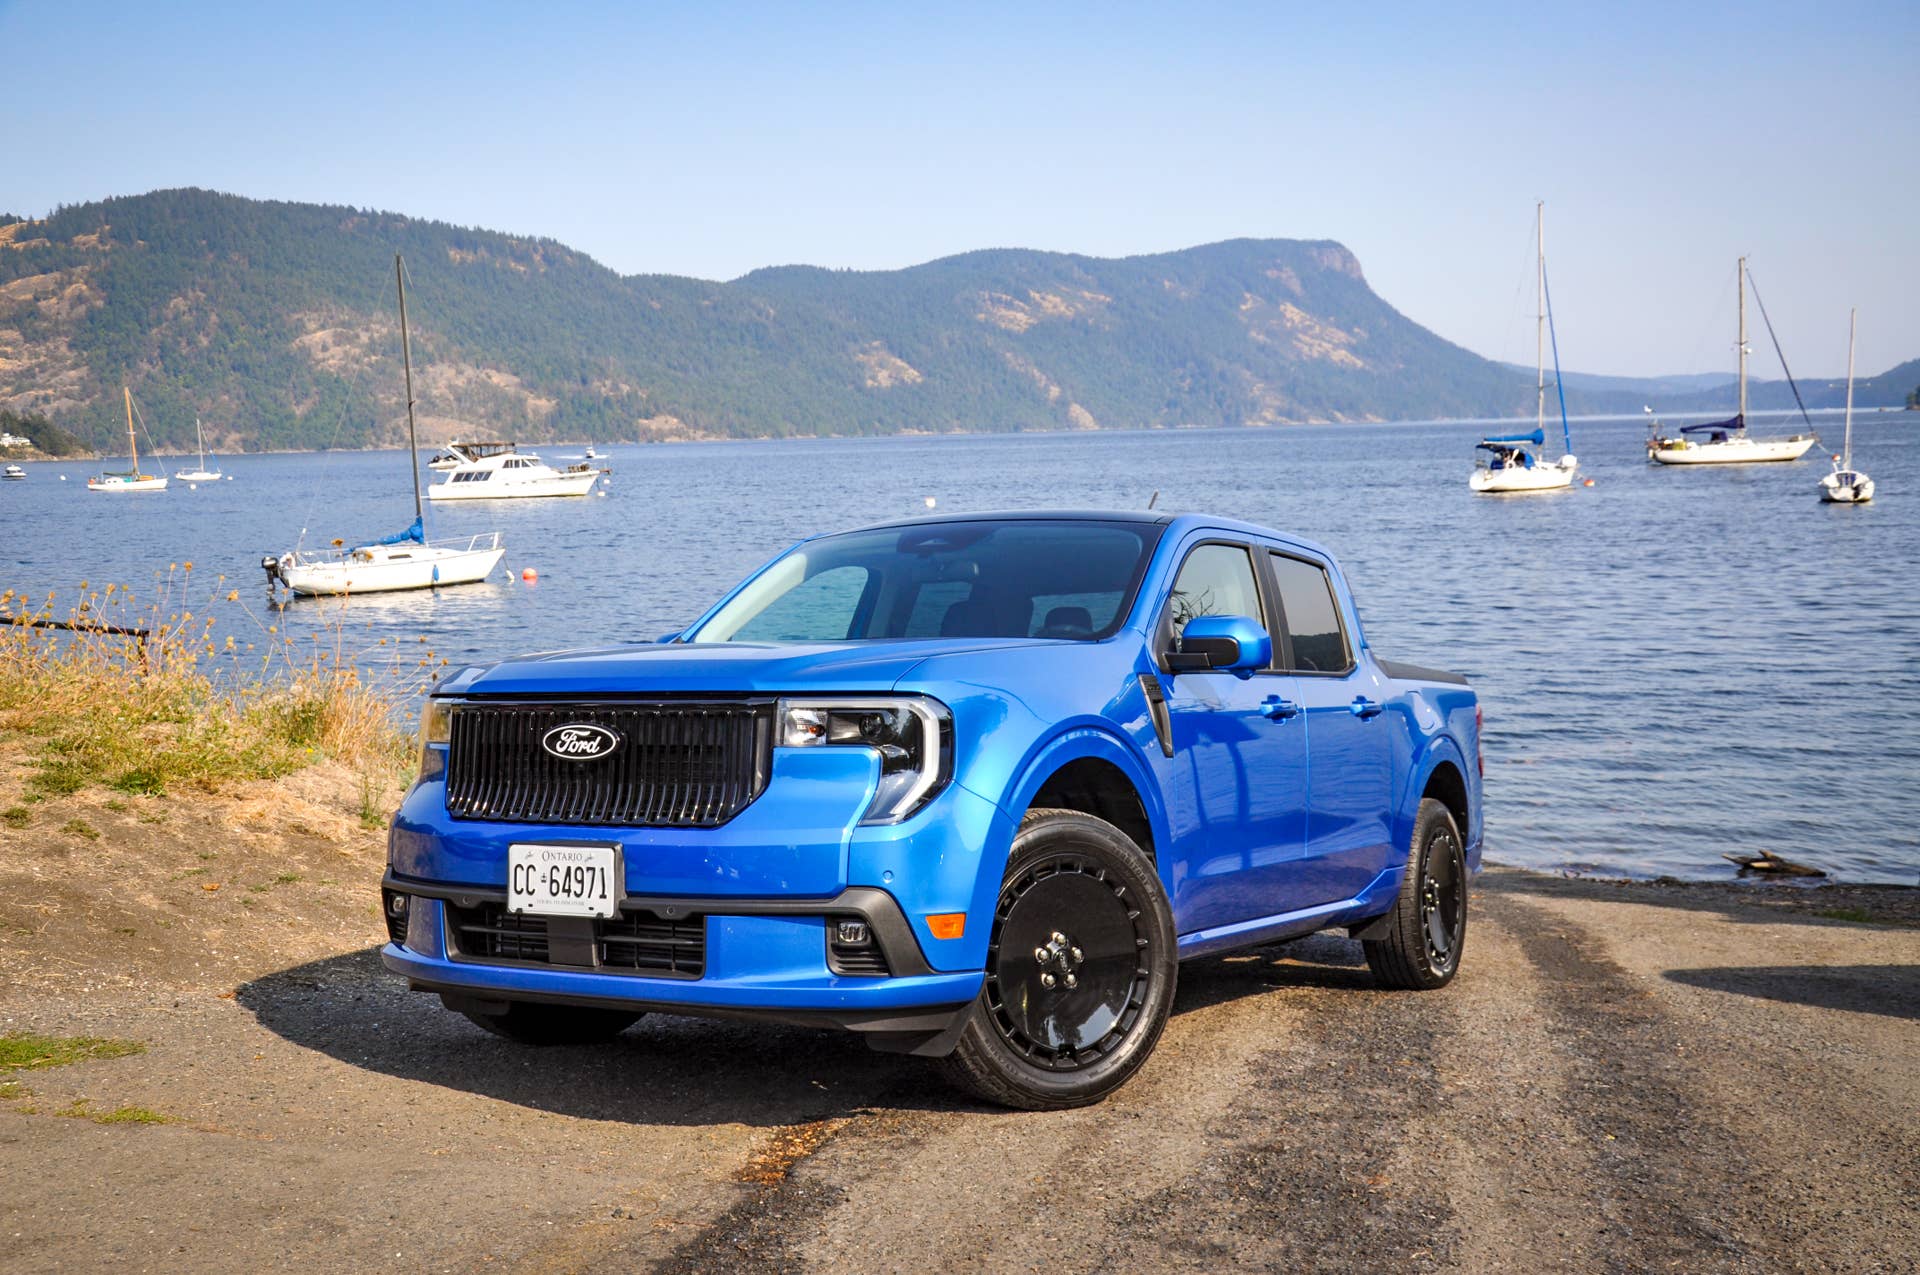
The Ford Maverick was meant to reset expectations. A compact pickup with a sub-$30,000 starting price, hybrid efficiency, and just enough capability to lure buyers out of sedans and crossovers. It was positioned as the antidote to bloated truck pricing. But in today’s market, even the Maverick is starting to reflect a different reality – one where “affordable” is more marketing than math.
New car prices have now pushed beyond the $50,000 mark on average, and that pressure is trickling down. Even entry-level vehicles like the Maverick are being pulled upward, not just by higher transaction prices but also by how they are financed. The result is a truck that still looks inexpensive on paper, yet ends up costing far more over time.
Cole Attisha
The Maverick Math Doesn’t Add Up
Take the 2025 Ford Maverick XL. Its MSRP is $28,145, but the estimated transaction price is $29,840. From there, the typical deal structure tells a different story: a $2,984 down payment and roughly $26,856 financed at 5.9% over 84 months.
That lands you at a seemingly reasonable $390 per month. On the surface, that is exactly what made the Maverick so appealing in the first place. But stretch that across seven years, and the total paid in monthly installments alone reaches around $32,760. Factor in the down payment, and you are looking at roughly $35,744 out of pocket. That is nearly $6,000 in interest on what is marketed as a budget-friendly pickup. The Maverick is still cheaper than most trucks, but the gap narrows significantly once financing is accounted for.
Cole Attisha
The Lowdown on 84-Month Loans
The biggest pitfall of an 84-month loan is negative equity. Vehicles depreciate fastest in the first three years, yet borrowers are barely chipping away at principal during that same window. If you need to sell or trade in early, you are likely underwater. Add rising interest rates, and the total cost balloons quickly, turning a budget-friendly compact pickup into a significantly more expensive proposition over time.
There is a narrow upside. If you are the type to keep a vehicle well past the loan term, an extended loan can reduce monthly strain and improve cash flow. But that requires discipline and long-term ownership. For many buyers, leasing a Maverick may actually be the smarter financial play, offering lower monthly payments and avoiding the burden of long-term depreciation. In a market where prices keep climbing, stretching loans may solve the short-term problem, but they create a much bigger one down the road.

Ford
About the author

Roy Robles
News Editor