On the surface, it seemed like Jill Colter had a slam-dunk case against a Nissan dealership she had accused of firing her because she had stage 4 cancer. Judges and juries, faced with such a sympathetic plaintiff versus a corporation, tend to favor the afflicted.
But after the case went to trial, a Massachusetts judge not only found in favor of the dealership, she ruled that Colter’s brothers had run a defamatory social-media smear campaign against the dealership that resulted in millions in lost business. She awarded Clay Nissan in Norwood, Mass. $1.5 million.
Protestors had picketed the dealership following her firing in June. Her brothers, Adam and Jonathan Colter, helped organize the boycott of the dealership. A dealership depends on a small market areas in the community in which it operates, so the bad publicity was devastating. Colter had been employed for 10 months with the dealership as a service writer when she was fired.
In leading the boycott, her brothers, Adam and Jonathan Colter, contended that the dealership had a history of firing employees with health problems. In court, the brothers could never prove that charge. The judge made that failure to produce the emails a key part of her decision.
“Of great significance to the court, when pressed by counsel for Clay about his assertions that Clay had fired others because they had cancer, Adam Colter insisted that he had received e-mails from other employees of Clay who had informed him that they had been fired by Clay because they had cancer.”
Judge Renee Dupuis of Norfolk Superior Court gave the Colter brothers a week to produce the emails, but they never did.
Next up was the issue of proving whether Colter was, indeed, singled out for firing because of her cancer. But employees at the dealership contended that Colter was difficult to work with and pointed to awkward interactions with customers as the reasons behind her dismissal. In a written statement that followed the decision, Clay Nissan said:
“We understand the anger on display about the incredibly emotional topic of the recent firing of an employee who has suffered from cancer. … The truth of the situation reflects – as you might expect – a much more balanced and human story.”
NOW CHECK OUT
Featured Gallery
Most car dealers are surely honest. But even honest ones have a great advantage on the buyer. They negotiate deals every day, and know all the tricks of the trade to maximize their profit.
Here are five things to know and avoid in your next new-car negotiations to save you big bucks and headaches.

Make sure you know your credit score before walking into a dealership because the deal you get on financing may depend on it. Let’s say a dealer has a special advertised deal, but in the small print the ad reads that it is only offered to”qualified buyers.” That means buyers with a high enough credit score.
Your credit score may, and probably will be, different depending on the service used. If your dealer is using one service has a lower credit score than another, they may use it to deny you the best deal, forcing you to pay more per month.
That is what happened to actor Dennis Singletary last year when a Valencia, Ca. Honda dealer denied him an advertised deal because they took the lower of two credit scores they checked.
The deal was for 0% down, low finance rates and monthly payments of $190. But the dealer, after disqualifying Singletary for the deal, offered him instead a deal that required $2,000 down and a $272 monthly payment. That’s a big difference.
What do you do? Singeltary went to a Hyundai dealer instead and bought his new wheels there.
Every sales person asks this question. And most customers answer it. Don’t.
By telling the sales-person what your monthly pain-point is for a car payment, you have given them a great advantage in the negotiation.
Instead, you want to know from a a site like AOL Autos what the dealer invoice price is, and negotiate the final cost of the vehicle. When you get the dealer to the lowest final transaction price he or she seems willing to take, then decide if the three, four, or five year loan will bring you to your monthly payment comfort point.
You should also know how much the manufacturer is offering in terms of national or regional rebates, which you can find by looking up the make and model vehicle you want on theAOL Autos research tool.
If you live in a salt-belt state (a state where salt and other road clearing chemicals are used to keep roads clean during the winter months) and intend to keep your vehicle for a long time, do consider having a professional rust protection done to the vehicle to keep rust and corrosion down.
But this is best done at detail shop, not buying the quickie rust-proofing sold by the dealer when you buy the car. A detailing, specialty shop does a much more thorough job. Visit one and have them explain the process.
Some dealerships will tell customers that they have to buy additional options or accessories for them to qualify for financing, a special interest rate or a reduced price. This is not an accepted business practice and may be illegal.
If there are dealer-sold accessories that you want–such as wheel covers, spoilers, body kits, luggage racks, light kits–you will probably do much better on price at a local accessories shop.
The thing you have to check first, though, is whether buying certain accessories outside the dealer will void the manufacturer warranty.
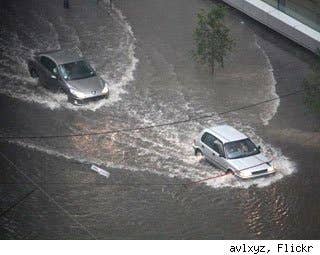
When there is flooding and damage to new cars on dealer lots as we have seen in Michigan and parts of the Southeast this year, water-damaged, new, cars can make their way back onto dealer lots.
There are unscrupulous vultures vying to buy as many (formerly) premium vehicles (Lexus, BMW, Cadillac) as they can at the lowest possible price. They will rebuild them as cheaply as possible and sell them back into the auction circuit. The auction buyer is their prey.
When these vehicles are sold back into the auction circuit, they are generally moved across the country, far from the location of the scoundrels that sold them. Purchased by some dealers and brokers, they are then taken to lots and sold as new or “almost new.”
It would be unusual to find these at a reputable big-time dealership in your area. But there are car brokers and lesser dealerships who sell both used and new cars who will advertise these cars as new..
So, what is going to happen to a flood damaged car? The vehicle may perform admirably for a few months, and then it slowly evolves into a money pit.
This worry obviously also applies to all used cars.
What to do? Check the Vehicle ID Number and cross-check for any discrepancies between the title, ID tag at the base of the windshield, and the tag on the driver’s door. Any differences could be an indication that the vehicle was given a new VIN after a flood total.
Take AOL Autos along with you to the dealer with our iPhone App! Click here to download it for FREE.